
Fitzroy River Corporation Ltd is a royalty holding company listed on the ASX under the code FZR. It’s had a relatively boring life as a listed company with its last dividend paid in December 2022, however it did return $0.02/share capital return in April 2025 (this is important & we will come back to it).
Why is this tiny, ~$18m market cap (AU$) company interesting then?
Its primary asset is a variable 1-3% Net Smelter Royalty (NSR) over the Blackwater Gold project in Reefton New Zealand. The mine, which is entering construction imminently, is expected to produce first gold in Q4 2026 & progressively ramp up production in 2027. Key metrics are below (taken from Endura Mining’s (the mine owner) website)

Importantly:
Endura Mining’s Board is stacked with seasoned gold mining professionals including Jake Klein (Founder and Non-Executive Chair of Evolution Mining) & Tony Kiernan AM (Genesis Minerals Chair), &
Has financial backing from Australian Super, the largest Superannuation Fund in Australia with >$385b of FUM
So, the Blackwater mine is managed by a proficient team who has executed on previous gold assets & has more than enough financial backing to see it into production.
Why not wait until there’s more clarity on the mine construction & production?
An interesting aspect of FZR’s NSR is that Endura mining has a buyback option that can be exercised at any time until a decision to mine for the sum of ~$11.9m (at 30 June 2025), where a decision to mine is defined as:
Being a date which is 20 business days after the date on which Federation (Endura):
Has access to sufficient funds to complete the development of the Snowy River Project (including construction of the Plant) and to proceed to commercial production; and
Holds in its bank account sufficient funds to pay the Buyout Price.
Interestingly, Endura posted this to their Facebook profile on September 28th. The second dot point is particularly interesting.
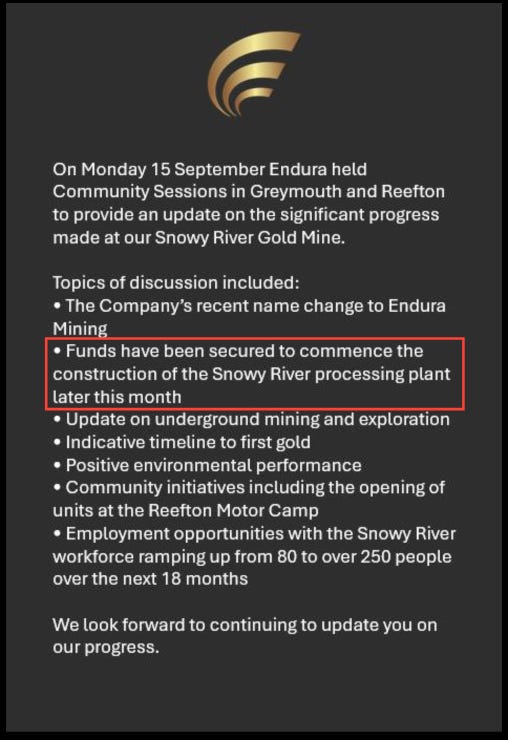
If we take that the ‘later this month’ statement on face value & conservatively assume it means the last day of September (Tuesday the 30th), 20 business days from them would be Tuesday the 28th of October. Therefore, FZR could feasibly receive ~$12m (the buyout price is indexed to Australian CPI quarterly, for simplicity I’ve just assumed a $12m price) by the end of October. This is 2/3 of the current market cap.
Will the royalty be bought back?
Looking at previous Federation Mining updates & a quick & dirty NPV calculation which puts the NPV10 (I’d say a gold royalty trades at a discount rate well below this, but let’s be conservative) of the royalty in the vicinity of $50m AUD (assuming a gold price of $3,000/oz vs the current price of >$4,000.oz) I’d sure bet that Endura will buy the royalty back!
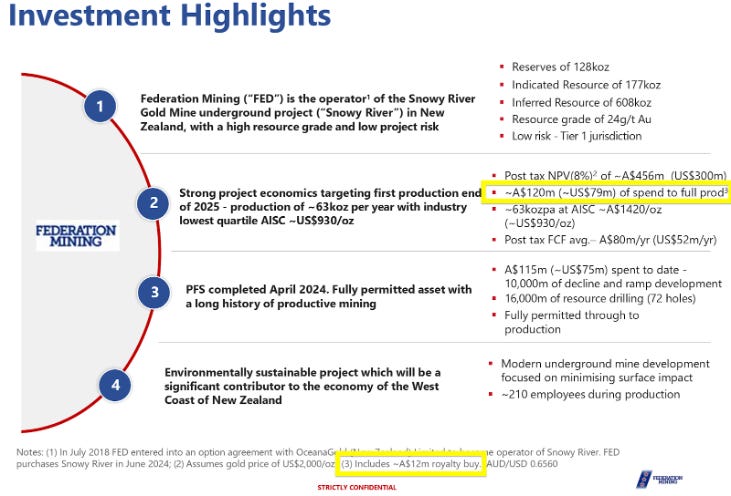
From Federation Mining’s October 2024 investor presentation - Slide 9 here
The other assets:
The balance of FZRs assets is a mix of gold, silver, oil & gas exposure & are summarised below:
1% of the ‘Weeks Royalty’ (a fascinating story for those interested, see here) which generates $550-600k p.a. to FZR
This cashflow is primarily used to pay for corporate expenses (although these are kept at a bare minimum, a credit to management) & was used to repay debt some years ago
A 1-2% NSR over the Bowden’s silver project in NSW
This is being developed by Silver Mines (SVL.ASX) & is currently going through NSW Government approvals (again) - Latest presentation is here
A 1% royalty on all products produced from the Sam’s Creek Gold Project on the South Island of New Zealand
This is being explored/developed by Siren Gold (SNG.ASX) - Latest presentation is here
A 2% net well head royalty over the tenements in the Canning Basin Royalty Deed, & a 3% net well head royalty over the tenements in the Lennard Shelf Royalty Deed
Both of these royalties are over gas prospects owned by Buru Energy (BRU.ASX) - Latest presentation is here
Effectively, the Weeks royalty cashflows have ‘'kept the lights on’ whilst FZR has waited for embedded value in the Blackwater royalty to be realised.
My estimate for the total NAV & my assumptions is below
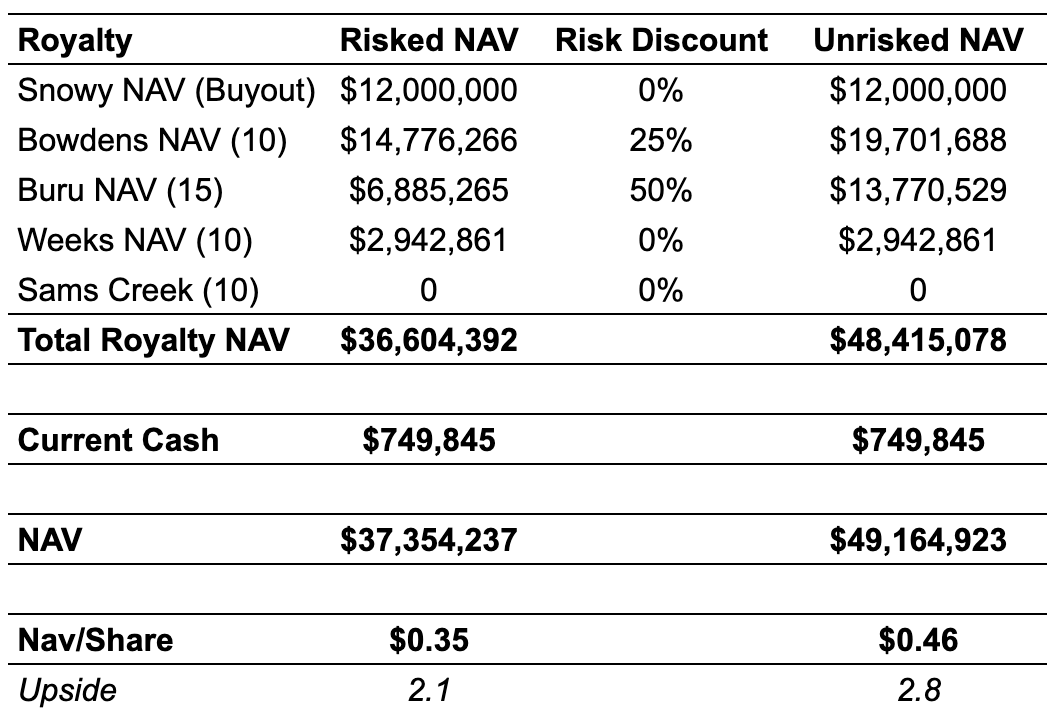
Assumptions:
Blackwater (Snowy)
Bought out for $12m (refer above)
Bowden’s
US$40/oz silver price (fixed across royalty life)
I note that current spot pricing is >$50/oz but it has run up a lot recently!
$0.65 AUDUSD FX rate (fixed across royalty life)
Production in line with latest forecast by Silver Mines - Slide 8 here
25% risk discount which seems about fair as I don’t think FZR wait for this to enter production & they seek a buyout from Silver Mines (which bought other royalties over the Bowden’s project in early 2020, see here)
Buru
This is flimsy I acknowledge as Buru is in the very early stages of building a small-scale LNG facility to service the Kimberly region in far Northern Western Australia
Buru have provided their estimated revenue forecasts over the life of the project - Slide 15 here
I’ve taken a very simple straight-line estimate of the royalty cashflow based on Buru’s revenue forecasts & discounted it back at 15%
50% risk discount on the above seems fair given the speculative nature of the royalty & the significant uncertainty around it
Weeks
$511k per annum until 2033 then no more cashflows
$511k is the minimum annual payment FZR has received since buying the 1% share of the overall royalty in 2015
The large assets that produce oil/gas that flow to the Weeks royalty are expected to cease production around 2033.
This could be extended if Woodside have exploration success (here) but I don’t see this as being meaningful in the bigger picture for FZR
No risk discount as the royalty is, & has reliably been, producing cashflow to FZR
Sams Creek
Simply valued at nil given the timelines proposed by Sirens Gold
Potentially value in the royalty but too much uncertainty for my liking, best case is FZR convince someone to buy it given the run up in the gold price recently
To summarise:
The current market cap of FZR is ~$18m & it looks highly likely they will have a ~$12m cash injection by the end of October
The ‘post blackwater’ Enterprise Value (‘EV’) is ~$4.3m (current market cap of ~$18m minus ~$12m from the blackwater buyout minus current cash of ~$700k)
At an EV of ~$4.3m you get:
~$150k p.a. of net Weeks cashflows (there are corporate expenses of ~$350k p.a. so a net $150k),
The strong probability of value realisation from the Bowden’s royalty within the near future, &
The option potential of Buru & Sam’s Creek Gold
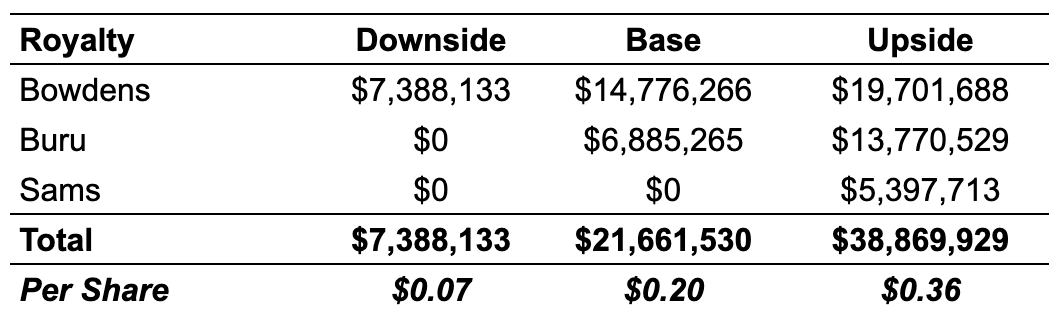
I think the above is probably worth between $7.4m and $39m depending on how optimistic I am with assumptions
Management have stated they would ‘evaluate further capital management initiatives for the benefit of all shareholders’ in the latest annual report.
I see this ‘capital management initiative’ as highly likely being a full return of the ~$12m via a capital return given the:
Historic precedent ($0.02 capital return in April 2025),
Share register is full of well renowned investment managers who would put up a very strong fight (cough … Sandon … cough, see here) if management tried to waste capital, &
The chair of the board, Susan Thomas, owns ~30% of FZR & has for several years
This effectively reduces the risk that whilst FZR receive the $12m from Blackwater, shareholders see some or none of it
I’ve personally been a buyer of FZR below $0.16 & currently own ~972,500 shares. I’m confident that the Snowy royalty will be bought out & the cash distributed to shareholders, from there I see two paths:
The quick resolution (& my base case given the register), being:
FZR approaches Silver Mines about buying out the royalty, which Silver Mines accepts given the accretion to their NAV, &
The remaining assets are privatised, potentially by Susan Thomas, at a discount to NAV
The slow burn, being:
All other royalties are progressively sold over the next few years as each underlying project reach sufficient milestones to realise value
I think we see a positive outcome by the end of 2026, potentially sooner if there is positive news from Bowden’s.
Make sure you DYODD & please correct me where I’m wrong!
LTC